 Kivulink
Bring your current rate. We will tell you straight.
Progressive, GEICO, Root, Bristol West and the specialty markets behind them, all quoting the same profile.
Texas statutory minimums. A single newer vehicle passes $25,000 without difficulty.
An SR-22 is a filing, not a policy.
This is the single most misunderstood thing in personal auto, and being confused about it costs people weeks.
An SR-22 is a certificate your insurance company files with the state to prove you carry at least the minimum required liability coverage.
You are not buying an SR-22. You are buying an auto policy, and asking the carrier to file the certificate alongside it. That is why "SR-22 insurance" as a product does not exist, and why the price you are quoted is just the price of a policy for a driver in your situation.
Usually required after driving without insurance, an at-fault accident while uninsured, a DWI, or an accumulation of violations, and in Texas it typically has to stay in place for two years.
If the policy lapses, the carrier notifies the state and the clock can start again, which is the part that catches people out.
Most standard carriers will not write these. The non-standard market will, and it is a market we already work in.
Bring the paperwork you were given, and tell us the actual reason for the filing rather than a softened version: it changes which carriers we approach, and getting it wrong wastes the week you probably do not have.
Texas requires liability of at least $30,000 per injured person, $60,000 per accident, and $25,000 for property damage. That is the legal floor, and the filing certifies you meet it. It is also low: a single new vehicle passes $25,000 without difficulty, and anything above the limit comes out of your own pocket. We will quote the minimum if that is what you need today, and we will say plainly what it does not cover.
Adding a teenager, without the ambush.
A new licensed driver is usually the largest single increase a household policy ever sees. Some of it is unavoidable and some of it is timing.
| Stage | What normally happens | Worth knowing |
|---|---|---|
| Learner's permit | Usually no extra premium. | Most carriers cover a permit holder under the existing policy at no additional cost. Tell your carrier anyway: doing it now avoids an argument later. |
| Newly licensed | The premium rises, often sharply. | This is the moment to re-shop the whole household rather than accept the increase. Carriers price young drivers very differently from one another, and the one that was cheapest for two adults frequently is not cheapest with a teenager on it. |
| Which car they drive | Changes the number materially | Assigning the new driver to the least expensive vehicle in the household usually costs less than assigning them to the newest one, and carriers differ on whether they let you choose. |
| Grades and driver training | Discounts available | Good-student and driver-education discounts are real and are commonly missed because nobody asks for them. Keep the transcript. |
| Moving out, or to college | May reduce it | A student living away from home without a car is often rated differently. This is worth telling your agent the week it happens, not at renewal. |
None of this is exotic. A captive agent has no reason to raise any of it with you, because they can only re-shop within one carrier. We can move the whole household, which is the only lever that matters at this moment.
Carriers disagree about you.
Premiums for comparable coverage commonly vary by hundreds of dollars a year between carriers for the same driver, because each one weighs your history, your address, your vehicle and your credit differently.
There is no such thing as a cheapest carrier in general, only a cheapest carrier for a particular person in a particular year.
So bring your current declarations page. We quote the same coverage across the carriers we hold, put them next to what you have now, and tell you honestly whether to switch or stay.
Sometimes the answer is stay, and saying so is the reason people come back to us when it is not.
Carriers pay our commission, which is set by them and is the same whichever one you choose. Coverage, discounts and eligibility vary by carrier and state, and no rate is final until a carrier has underwritten the application.
Compare my auto rateAuto questions, answered.
Can I get auto insurance without a Social Security number?
In many cases yes. Several carriers accept an ITIN, and a valid driver's licence matters more than the number. It narrows the field of carriers rather than closing it, which is exactly what an independent agency is for.
Will an accident or a ticket follow me forever?
No. Most violations affect your rate for three to five years depending on the carrier and the offence, and they age off.
Re-shop when a major one drops off your record, because the carrier you are with will not necessarily volunteer that it has.
Does my personal policy cover me for delivery or rideshare driving?
Usually not. Most personal auto policies exclude driving for hire, and the gap is wider than people assume. If you drive for any platform, tell us so we can quote the endorsement or the commercial policy that covers it.
Is the minimum liability enough?
It is enough to be legal. Whether it is enough to protect you is a different question, and the honest answer for most households with anything to lose is no. We will show you what the next step up costs before you decide, and it is often less than people expect.
My rate went up and nothing changed. Why?
Carriers re-rate whole books for reasons that have nothing to do with you: repair costs, local claims, changes to their own model. A rate rise you did not cause is the most common reason to shop, and the least likely to be explained to you in the renewal letter.
Auto carriers we hold 4+

One application is rated by all of them. Appointments vary by state and no carrier writes every product everywhere. See the full network.
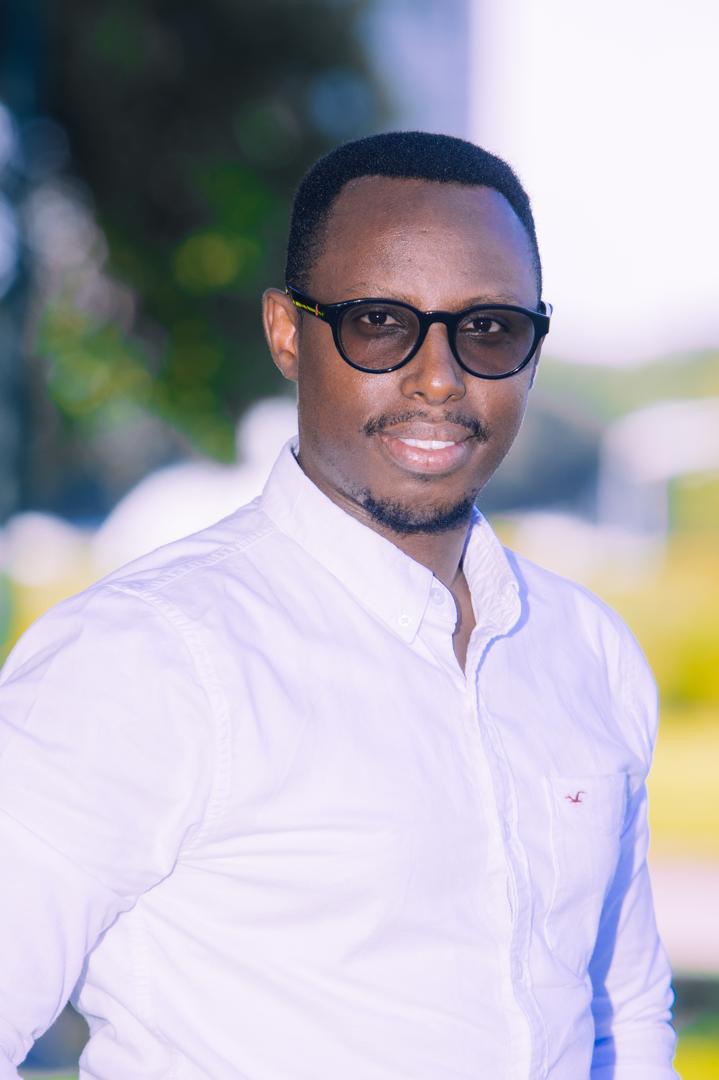 Written and reviewed by Innocent Muvunyi, Licensed Insurance Agent.
NPN 22182172. AHIP certified, CMS FFM registered.
Last reviewed .
Check this licence with the Texas Department of Insurance.