 Kivulink

The exclusions matter more than the price.
Two things decide whether a Houston homeowner is covered, and neither is the monthly premium.
Flood is a separate policy. Always.
Your homeowners policy does not include it, and there is no rider that adds it.
Every standard homeowners policy in the United States excludes flood.
That is not a gap your carrier chose; it is how the product is built nationwide. Water that comes down through a damaged roof is generally a homeowners claim. Water that rises from the ground into the house is a flood claim, and it is not covered unless you hold a separate flood policy.
In a city that has been through what this one has, that distinction is the difference between a repaired house and a ruined one, and it is decided in the minutes after the water arrives by a document you either bought or did not.
A new National Flood Insurance Program policy generally does not take effect for 30 days.
By the time a storm has a name and a forecast track, the window has already closed. This is why flood is bought in February, not in August. Some private flood policies have shorter waits, and there are narrow exceptions such as a policy required at closing, but nobody should plan around them.
You do not have to be in a mapped high-risk zone to flood, and a large share of claims come from outside those zones.
Being outside one usually means the policy is cheaper, not that you do not need it. We can look up your address, tell you which zone you are in, and quote both the NFIP and the private market, which now often beats it.
Waiting periods, eligibility and rates are set by the National Flood Insurance Program and by private carriers, and they change. Confirm yours at floodsmart.gov or ask us to check the address.
Check my flood zoneYour roof has its own deductible.
Most Texas policies carry a separate wind and hail deductible, written as a percentage rather than a dollar amount. The two look alike on paper and behave very differently.
| On the declarations page | What you pay on a roof claim | What to watch |
|---|---|---|
| A flat dollar deductible | The stated amount, whatever the house is insured for. | Predictable. Less common on wind and hail in Texas. |
| A percentage deductible | That percentage of the dwelling coverage amount, not of the claim. | A 2% deductible on a house insured for $300,000 is $6,000 out of pocket before the policy pays anything. |
| Roof settlement basis | Replacement cost pays what a new roof costs. Actual cash value pays that minus depreciation for the roof's age. | On an older roof, actual cash value can pay a fraction of the replacement bill. This clause is often what makes one quote cheaper than another. |
Those three lines explain nearly every "my policy was cheaper but it did not pay" story we hear.
When we compare quotes we put them side by side, because a lower premium bought by moving to actual cash value on a fifteen-year-old roof is not a saving, it is a transfer of risk back to you that nobody mentioned.
Renters insurance is the cheapest policy we sell.
Your landlord's policy covers the building. It covers nothing of yours inside it, and it does not cover you if someone is hurt in your unit.
Renters insurance does both, plus it pays for somewhere to stay if the unit becomes uninhabitable, and it is routinely the least expensive policy anyone in this office buys.
It is also the one most often skipped, usually by people who would be hardest hit by losing everything they own at once. If you rent and you have never held it, it is worth the five minutes it takes to ask.
If you own a property you rent out, that is a landlord policy rather than a homeowners one, and putting a tenant in a house still insured as owner-occupied is a coverage problem waiting for a claim to expose it. Tell us when the use of a property changes.
Quote renters coverageHome coverage questions, answered.
I am not in a flood zone. Do I still need flood insurance?
Everywhere is in a flood zone; the question is which one.
Outside the mapped high-risk areas a policy is usually much cheaper, and a substantial share of claims come from exactly those lower-risk zones. Cheap is a reason to buy it, not a reason to skip it.
My mortgage company says I have enough coverage. Is that the same thing?
No. A lender cares that the loan is protected, and nothing more. It says nothing about your belongings, your liability, where you would live during repairs, or whether your roof settles at replacement cost.
Does home insurance cover a leaking roof?
Sudden damage, usually yes. Gradual wear and failure to maintain, generally no. This is the most common denial we see, and the difference is often decided by the roof's age and condition at the time of the claim.
Will filing a small claim raise my premium?
It can, and claims stay on your record for years across carriers. For damage close to your deductible it is worth a conversation before you file. We will give you an honest answer even when the answer is not to claim.
Can you review the policy I already have?
Yes, free, including one bought elsewhere. Send the declarations page and we will read the deductibles, the settlement basis and the exclusions and tell you plainly what it would and would not do.
Home and renters carriers we hold 4+
Also Swyfft and more.
One application is rated by all of them. Appointments vary by state and no carrier writes every product everywhere. See the full network.
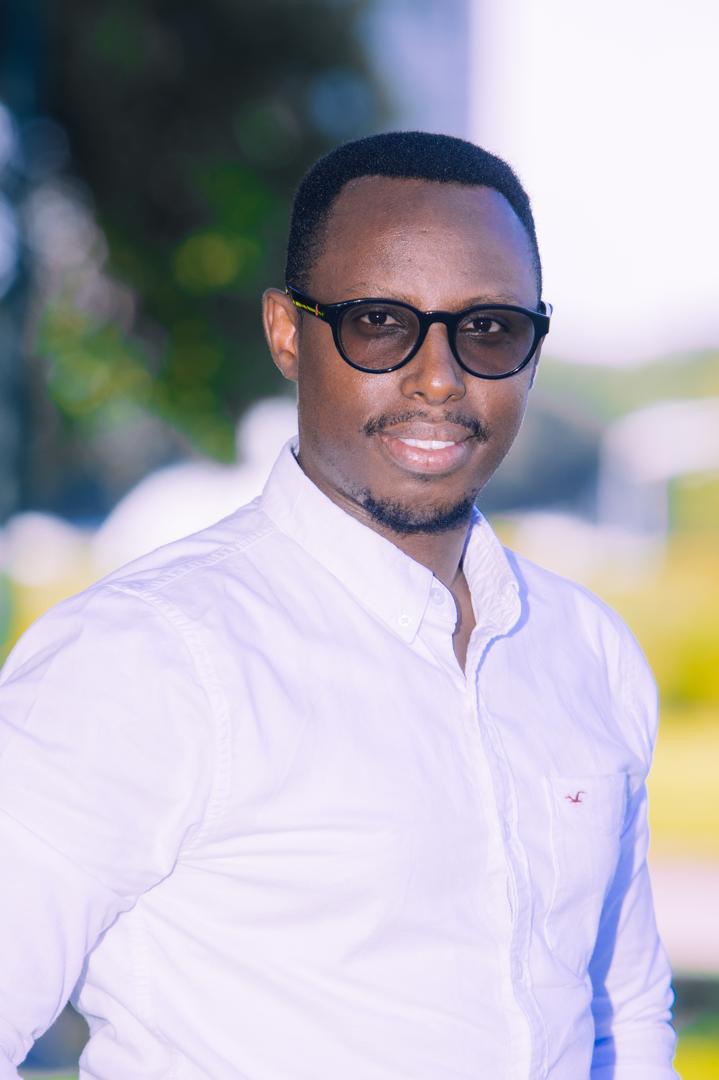 Written and reviewed by Innocent Muvunyi, Licensed Insurance Agent.
NPN 22182172. AHIP certified, CMS FFM registered.
Last reviewed .
Check this licence with the Texas Department of Insurance.